
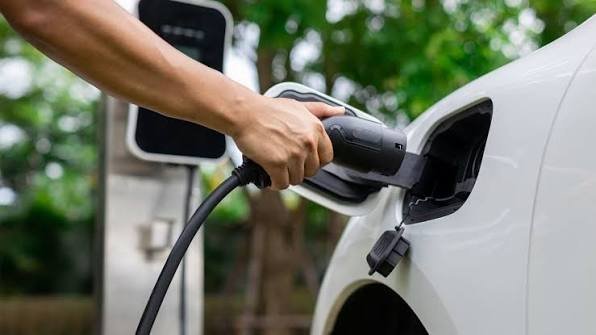
India’s transition to electric mobility has made remarkable strides, with EV penetration rising from a mere 0.5% in 2018 to 8.25% in 2025–26. Yet, a striking dichotomy defines the market: while commercial EV adoption is surging (reaching up to 61% in states like Tripura, largely driven by public fleets and government-backed e-buses), private EV adoption hovers at a modest 12% even in leading states like Kerala and Goa.
Key Factors Fueling Private Owner Skepticism
-
The Infrastructure Disconnect: While some regions boast high public charger-to-vehicle ratios (such as Delhi and Karnataka), charging network availability remains deeply uneven nationwide. For private owners—particularly those lacking dedicated home or apartment parking with charging setups—”range anxiety” remains a primary deterrent.
-
Asymmetric Growth vs. Commercial Fleets: Much of India’s headline EV growth is concentrated in commercial segments (two-wheeler delivery fleets, three-wheeler auto-rickshaws, and public transit buses). Commercial operators follow predictable daily routes and benefit heavily from centralized depot charging, a luxury private owners often lack.
-
Upfront Costs and Resale Uncertainties: Despite long-term operational savings, the higher upfront sticker price of private electric cars and two-wheelers, combined with evolving battery technology and uncertain secondary resale markets, makes individual buyers cautious.
-
Pacing and Model Availability: Market availability for specific private vehicle segments (especially affordable private four-wheelers) has historically faced pacing bottlenecks, as manufacturers prioritize higher-margin commercial or premium lines.
