
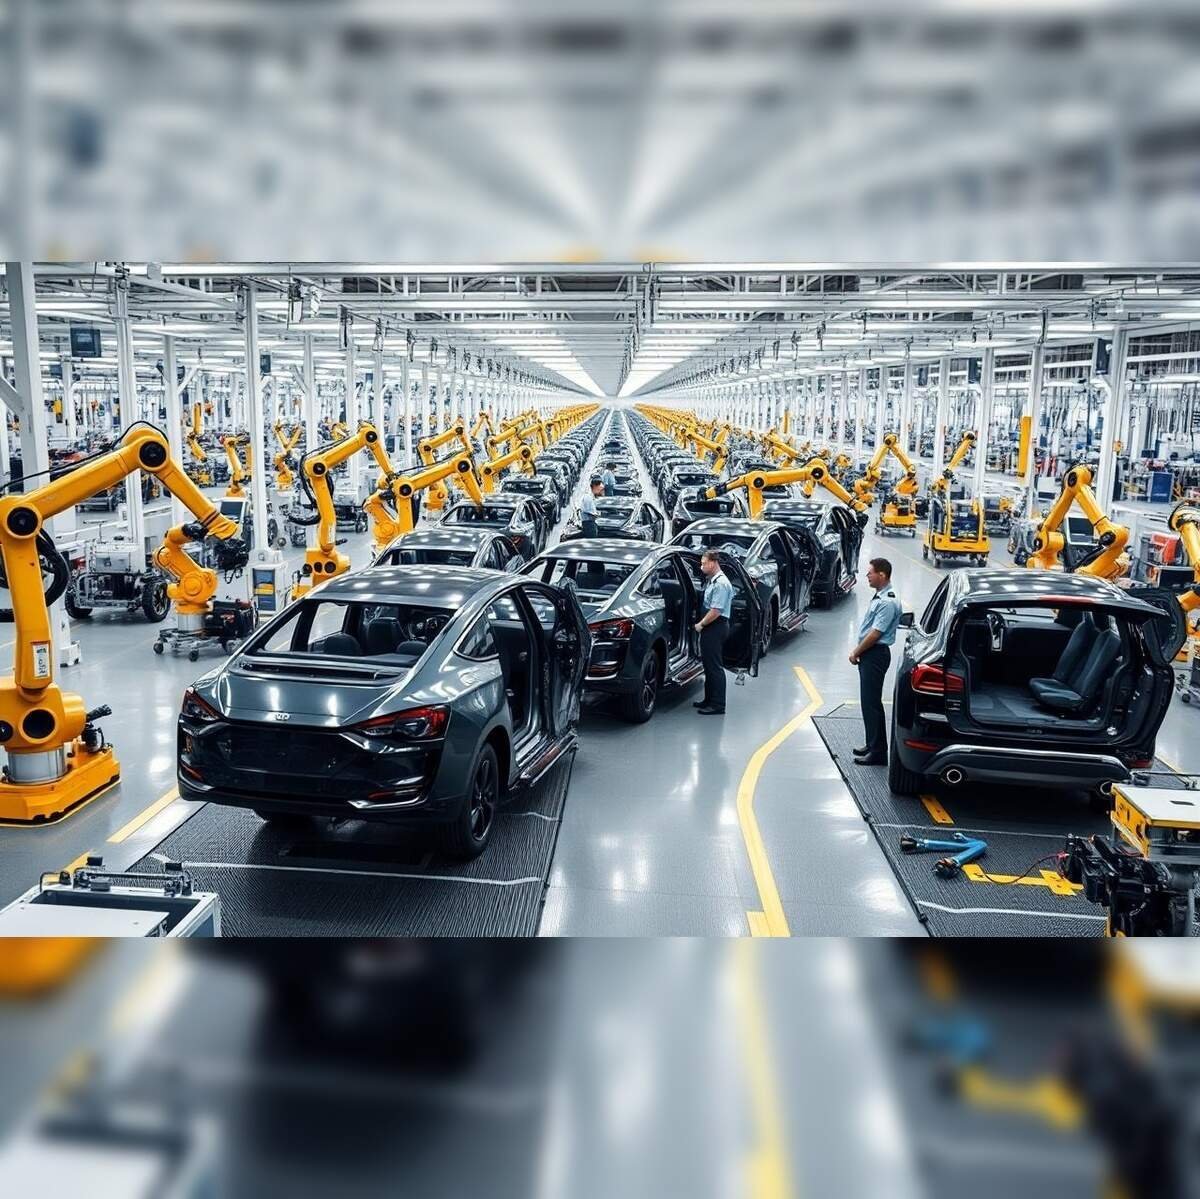
The automotive industry is often judged by the sleek exteriors rolling off assembly lines or the horsepower figures that capture headlines. Yet, beneath the sheet metal lies a vast, intricate ecosystem of specialized component manufacturers—the auto ancillaries that quietly dictate the reliability, efficiency, and ultimate profitability of global mobility. Reaching the milestone of eighty editions in this series reveals a sector undergoing profound structural shifts, where traditional manufacturing prowess must now intersect with aggressive global supply chain integration, technological adaptability, and capital discipline.
The Evolution of the Ancillary Business Model
A few years back, the primary strategic question facing many mid-tier and specialized auto ancillary suppliers was a classic scaling dilemma: Would heavy capital expenditures in new plant capacities, R&D, and multi-region customer programs eventually translate into top-line revenue?
Historically, component makers operated in cyclical, low-margin environments heavily dependent on domestic original equipment manufacturer (OEM) schedules. The playbook relied on incremental volume growth and strict cost control. However, the contemporary landscape demands a complete reinvention. Successful players are no longer simple build-to-print vendors; they are co-development partners embedded deeply in the global product lifecycles of major passenger, commercial, and electric vehicle manufacturers.
-
Capital Expenditure Maturation: Early-stage investments in automation, lightweighting capabilities, and precision tooling are finally bearing fruit, shifting plants from capital-drain phases to high-utilization cash generators.
-
Geographic Diversification: Mitigation of domestic cyclicality has been achieved through aggressive export market penetration, particularly into North American, European, and East Asian supply chains seeking “China-plus-one” manufacturing redundancies.
-
Value-Chain Upgradation: Suppliers transitioning from commoditized, low-margin mechanical parts to complex assemblies, electronic integration, and thermal management systems are seeing structural margin expansions.
Dissecting the Financial Inflection Point: Repeatable Growth vs. Cyclical Windfalls
When an auto ancillary supplier reports a record-shattering quarter driven by a combination of surging annual revenues, expanding export volumes, and a massive overseas-linked order, financial analysts face a critical analytical test: Differentiating secular growth from cyclical anomalies.
To determine whether a company is poised for sustained multi-year outperformance or simply enjoying a temporary market aberration, stakeholders must evaluate several core financial and operational vectors:
The Macro Headwinds and Sector-Wide Divergence
The broader macroeconomic environment remains fraught with friction. Elevated interest rates, volatile raw material costs, shifting trade policies, and an uneven global EV adoption curve mean that a rising tide no longer lifts all boats. In fact, the auto ancillary space is experiencing a sharp bifurcation:
-
The Vulnerable Tier: Smaller suppliers lacking technological depth or pricing power continue to struggle with margin compression, high debt service costs, and customer concentration risks.
-
The Resilient Leaders: Well-capitalized, technologically agile companies are leveraging their balance sheets to capture market share left vacant by distressed competitors, turning industry disruption into a distinct competitive advantage.
As this series demonstrates across its diverse analyses, understanding an auto ancillary business requires looking past headline quarterly numbers. It demands an examination of engineering moats, customer stickiness, and the ability to execute operationally when global macro currents turn turbulent. The ultimate fate of these stocks will not be decided by single-quarter surprises, but by the relentless, compounding momentum of their underlying operational numbers.
