
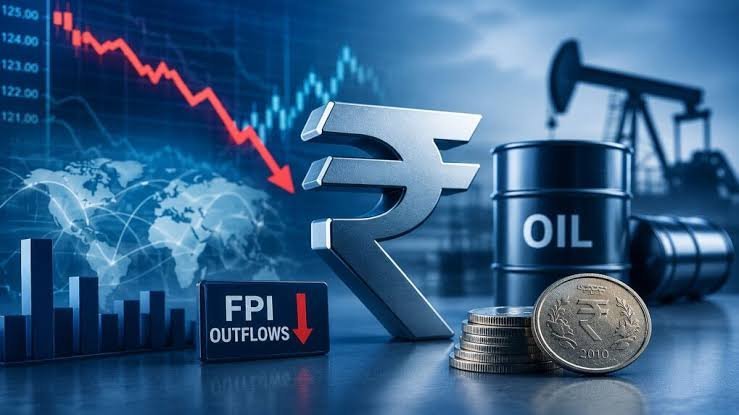
The discussion on crude oil prices and macroeconomic volatility highlights a critical dilemma for investors: sentiment vs. core fundamentals.
When geopolitical tensions in the Gulf push oil prices higher, inflationary pressures follow. For banking stocks, this dynamic triggers a two-pronged challenge:
-
FPI Outflows & Selling Pressure: Because Indian banks (especially large-cap private lenders) feature heavily in Foreign Portfolio Investor (FPI) portfolios, they are often used as liquidity proxies. When global risk-off sentiment spikes due to oil or US policy shifts, institutional selling can depress stock prices well before underlying business metrics take a hit.
-
Margin and Credit Impact: Sustained high inflation can force central banks to keep interest rates elevated longer, affecting credit growth, increasing cost of funds, and putting pressure on Net Interest Margins (NIMs).
Separating the Stock from the Business
The crucial takeaway is recognizing the gap between market noise and business health. While stock prices experience knee-jerk corrections due to foreign fund flows or global headlines, fundamentally strong banks with robust credit growth, low Non-Performing Assets (NPAs), and solid provisioning cushions often use these volatile phases to build long-term value.
When analysts point toward double-digit upside potentials (such as the 27% projections often cited across select public and private banking portfolios), they are typically looking past short-term crude fluctuations and pricing in:
-
Strong Balance Sheets: Low credit costs and well-capitalized buffers that insulate banks against macroeconomic shocks.
-
Credit Demand Resilience: Ongoing retail and corporate credit expansion within the domestic economy.
-
Valuation Comfort: Corrections driven by macro fears often leave fundamentally sound counters trading at attractive entry points relative to their historical price-to-book valuations.
