
When evaluating a company’s financial health, investors naturally look at the headline net profit or loss. But as recent corporate investigations show, a reported loss of ₹162 crore can sometimes mask an underlying bleeding of nearly ₹8,000 crore.
How is such a staggering discrepancy possible? Through legal accounting maneuvers that rely on labels, classifications, and stale valuations that almost nobody questions.
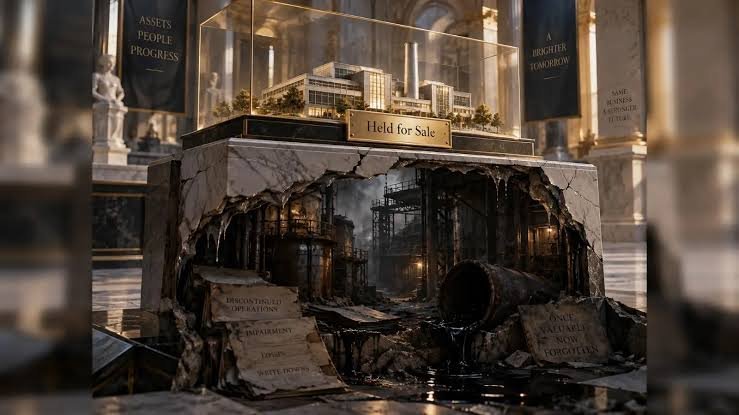
The Magic Label: “Held for Sale”
Imagine looking at a company’s balance sheet and discovering that half of everything it owns sits under a single, innocuous label: “Held for sale.”
Under standard accounting rules, when a company intends to dispose of a business segment or a major asset block, it reclassifies those assets. But here lies the trick:
-
Stale Valuations: Once an asset is bucketed as “for sale,” depreciation and routine revaluations often stop. Even if the market value of those assets has plummeted, the books can continue to show an outdated, inflated price tag for years.
-
Disappearing Running Costs: Operating expenses associated with keeping those distressed assets alive can vanish from the primary headline numbers, slipping out of sight while the business continues to bleed cash.
-
The Ghost Deal: In some instances, the actual deal to sell those assets may have collapsed years prior, with the prospective buyer long gone. Yet, the assets remain safely parked in the “for sale” category, shielding the P&L statement from the harsh reality of write-downs.
Why Investors Need to Look Beyond the Headline
When companies utilize these accounting loopholes, the headline loss becomes a fraction of the economic reality. For everyday shareholders, trusting the surface-level net profit or loss without digging into asset classifications and footnotes can lead to a severely distorted view of a company’s solvency.
